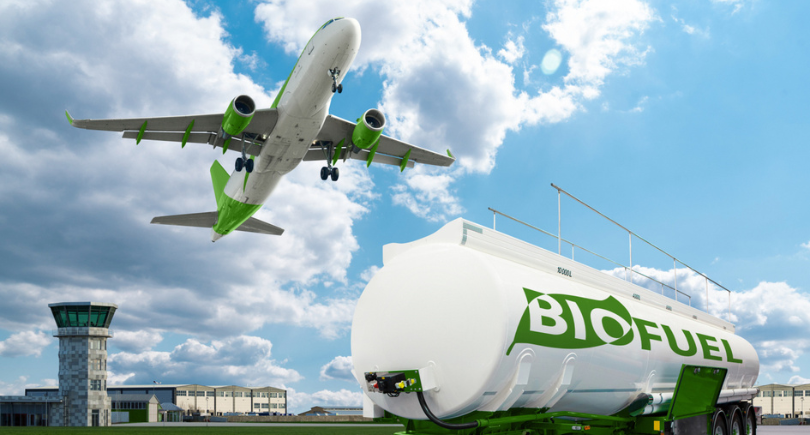

The aviation industry is entering a defining phase in its journey toward decarbonisation. While airlines continue investing in fuel-efficient aircraft, fleet modernisation, and operational efficiencies, Sustainable Aviation Fuel (SAF) is increasingly viewed as the most practical near-term solution for reducing aviation emissions at scale.
However, the SAF market is evolving rapidly beyond its early foundations of biofuel production from used cooking oil and agricultural waste. A broader transformation is now underway — one shaped by environmental attribute trading, methanol-to-jet technologies, renewable natural gas pathways, and large-scale industrial integration strategies.
Recent developments across Japan, India, the United Kingdom, and the United States highlight how SAF is transitioning from a niche sustainability initiative into a major global industrial and energy opportunity.
Scaling Production Remains SAF’s Greatest Hurdle
Despite growing political and commercial momentum, SAF still accounts for only a very small share of global aviation fuel consumption. Across the industry, one issue continues to dominate discussions: scale.
Most SAF production today relies on Hydroprocessed Esters and Fatty Acids (HEFA) technology, which uses feedstocks such as used cooking oil, vegetable oils, and animal fats. While this pathway has enabled the industry’s early SAF adoption, feedstock limitations are becoming increasingly apparent.
As global aviation demand grows, existing feedstock supplies alone will not be sufficient to support long-term SAF expansion.
This reality is driving governments, refiners, technology companies, and energy producers to explore alternative production methods capable of generating significantly larger fuel volumes. As a result, the SAF sector is rapidly diversifying both technologically and commercially.
SAF Certificates Could Transform the Market
One of the most significant developments emerging within the sector is the growing use of SAF environmental attribute trading systems.
ITOCHU Corporation recently completed a SAF environmental attribute transaction with Future Energy Global, enabling emissions reduction benefits associated with SAF usage to be traded independently from the physical fuel itself.
The model closely resembles renewable energy certificate systems already widely used in electricity markets. Under this approach, SAF may be physically delivered and consumed at one airport while the associated environmental credits are purchased by an airline or corporate customer operating elsewhere.
Supporters believe this mechanism could accelerate SAF adoption by creating more flexible and commercially scalable pathways for participation in the market. Critics, however, continue raising concerns around traceability, accounting standards, and the potential risk of double counting emissions reductions.
Even so, the concept is gaining momentum because it offers a possible solution to one of SAF’s biggest logistical challenges: uneven fuel availability across global airport networks.
Renewable Natural Gas Expands the SAF Feedstock Debate
At the same time, Renewable Natural Gas (RNG) is emerging as another important SAF feedstock pathway.
Research published by the Kleinman Center for Energy Policy explored how methane captured from landfills, wastewater treatment facilities, and agricultural waste streams could be converted into sustainable aviation fuel while simultaneously reducing methane emissions.
The “waste-to-wing” concept is attracting growing industry attention because methane is considered significantly more harmful than carbon dioxide over shorter climate timeframes. Capturing methane and converting it into aviation fuel could therefore generate meaningful lifecycle emissions reductions.
However, experts caution that the environmental credibility of RNG-based SAF depends heavily on accurate carbon accounting, feedstock traceability, and effective methane leakage management.
Nevertheless, RNG presents an important strategic advantage by leveraging existing gas infrastructure while opening new decarbonisation opportunities for agriculture, waste management, and energy sectors simultaneously.
Methanol-to-Jet Technologies Gain Momentum
Among the most closely watched next-generation SAF pathways is Methanol-to-Jet (MtJ) technology. Essar Energy Transition recently advanced one of the UK’s largest proposed SAF developments at the Stanlow Refinery, where a new facility aims to produce more than 200,000 tonnes of SAF annually using renewable methanol feedstocks.
A key advantage of the Stanlow project lies in its integration within an existing refinery ecosystem. By utilising established storage, blending, logistics, and distribution infrastructure, the project reflects a broader industry trend of repurposing traditional energy assets for low-carbon fuel production.
Methanol-based SAF technologies are also drawing increased attention in Europe and Australia as developers search for scalable alternatives to conventional bio-oil feedstocks.
Despite the growing interest, MtJ pathways still face several commercial and technical challenges, including certification requirements, process efficiency, feedstock sourcing, and production economics. Industry stakeholders continue working toward broader ASTM approvals and commercial-scale deployment pathways.
India Is Positioning Itself as a Future SAF Hub
India is increasingly emerging as a potentially important player in the global SAF landscape. The country’s rapidly expanding aviation market, strong refining sector, established ethanol ecosystem, and evolving biofuel policies are creating favourable conditions for SAF investment and development.
Several initiatives are already taking shape:
- IndianOil is progressing SAF programmes linked to refinery integration and used cooking oil feedstocks.
- Ethanol-to-jet fuel developments are being explored in Andhra Pradesh with government and industry participation.
- Additional SAF projects involving agricultural residues and renewable feedstocks are also under evaluation across the country.
India’s SAF strategy carries broader economic significance because it aligns decarbonisation objectives with energy security goals. Expanding domestic SAF production could help reduce jet fuel import dependence while simultaneously creating new industrial value chains linked to agriculture, waste utilisation, and renewable energy.
India’s extensive ethanol production infrastructure may also provide a competitive advantage for Alcohol-to-Jet (AtJ) fuel pathways compared with markets lacking large-scale bioethanol capacity.
SAF Is Evolving into an Infrastructure Competition
One of the clearest global trends is that SAF is no longer viewed solely as an airline sustainability initiative. Increasingly, it is becoming part of a wider industrial infrastructure race.
Governments and industry stakeholders now see SAF production capacity as strategically linked to:
- Energy security
- Industrial competitiveness
- Aviation sector growth
- Emissions reduction targets
- Hydrogen and renewable energy expansion
- Advanced manufacturing capability
This growing strategic importance explains why many countries are introducing SAF mandates, production incentives, grants, subsidies, and tax support mechanisms to accelerate investment.
The UK, for example, is targeting SAF to account for 22% of jet fuel demand by 2040 under its emerging SAF mandate framework. Meanwhile, airlines face mounting pressure from regulators, investors, and corporate customers to demonstrate credible long-term decarbonisation strategies.
The Next Decade Will Shape Aviation’s Fuel Transition
The SAF industry is now approaching a critical inflection point.
Technology pathways are advancing, investor interest continues to increase, and regulatory frameworks are gradually becoming more supportive. Across the aviation sector, there is growing recognition that large-scale SAF deployment will be essential if the industry is to achieve long-term climate objectives. Yet major obstacles remain.
Feedstock availability, infrastructure readiness, hydrogen supply, certification timelines, production costs, and lifecycle emissions accounting will all influence how quickly SAF can scale globally. What is becoming increasingly apparent is that no single technology pathway will dominate the future SAF market.
Instead, the sector is likely to evolve through a combination of:
- HEFA fuels
- Alcohol-to-Jet technologies
- Methanol-to-Jet production
- Renewable natural gas integration
- Power-to-liquid synthetic fuels
- Environmental attribute trading systems
The aviation fuel transition is no longer theoretical. It is already underway — and the global race to build the next generation of sustainable aviation fuel infrastructure is accelerating rapidly.